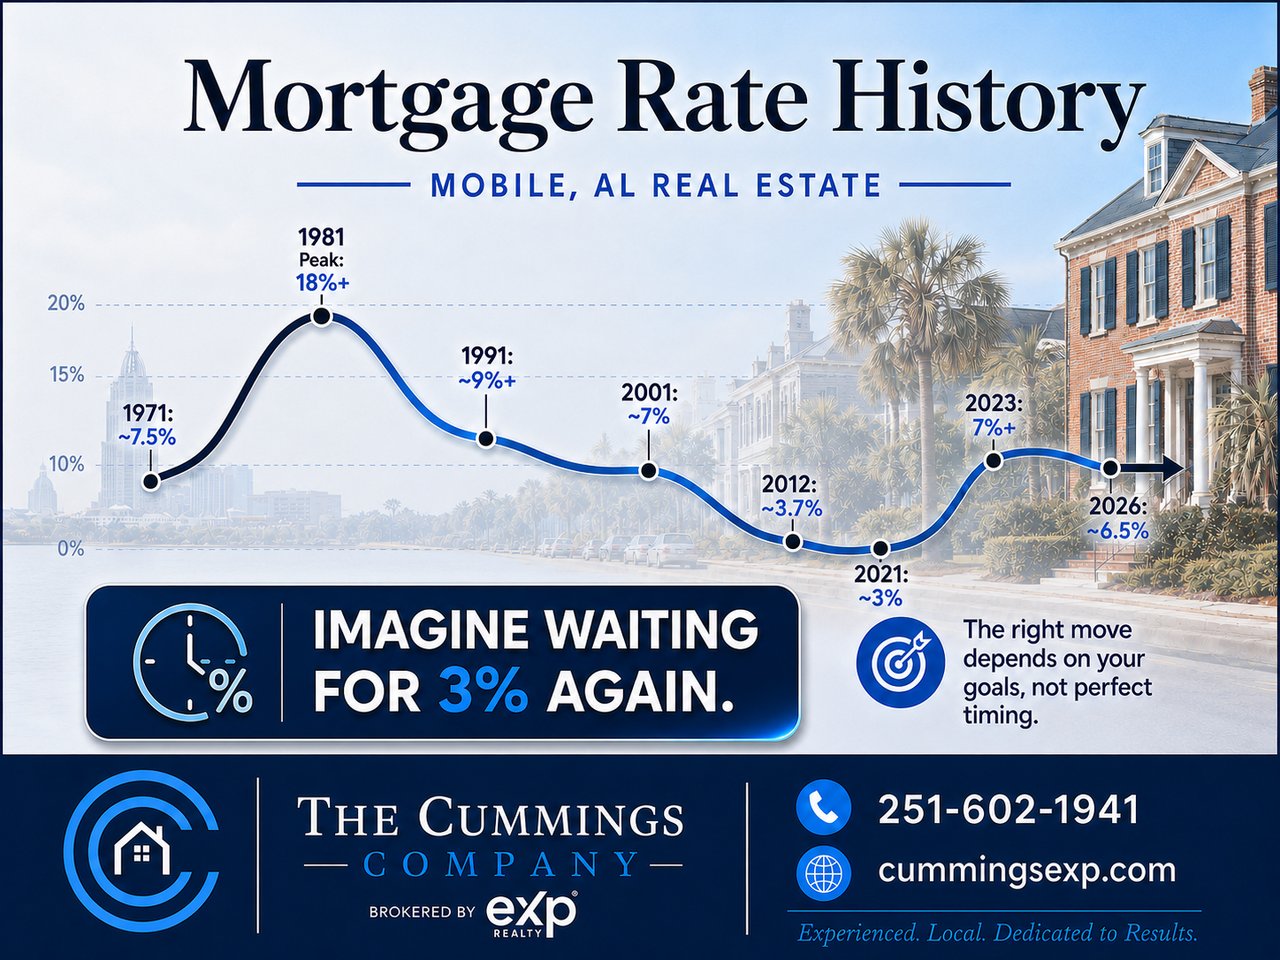
If you've been holding off on buying a home in Mobile, Alabama because you're waiting for mortgage rates to drop, you're not alone. Thousands of families across the Gulf Coast are doing the same thing — watching rates, watching the market, and waiting for that "perfect" moment to buy.
But here's what the data actually shows: waiting may already be costing you more than you realize.
This post breaks down the real financial impact of sitting on the sidelines in Mobile's housing market right now, and what smart buyers are doing instead.
What's Happening With Mortgage Rates Right Now?
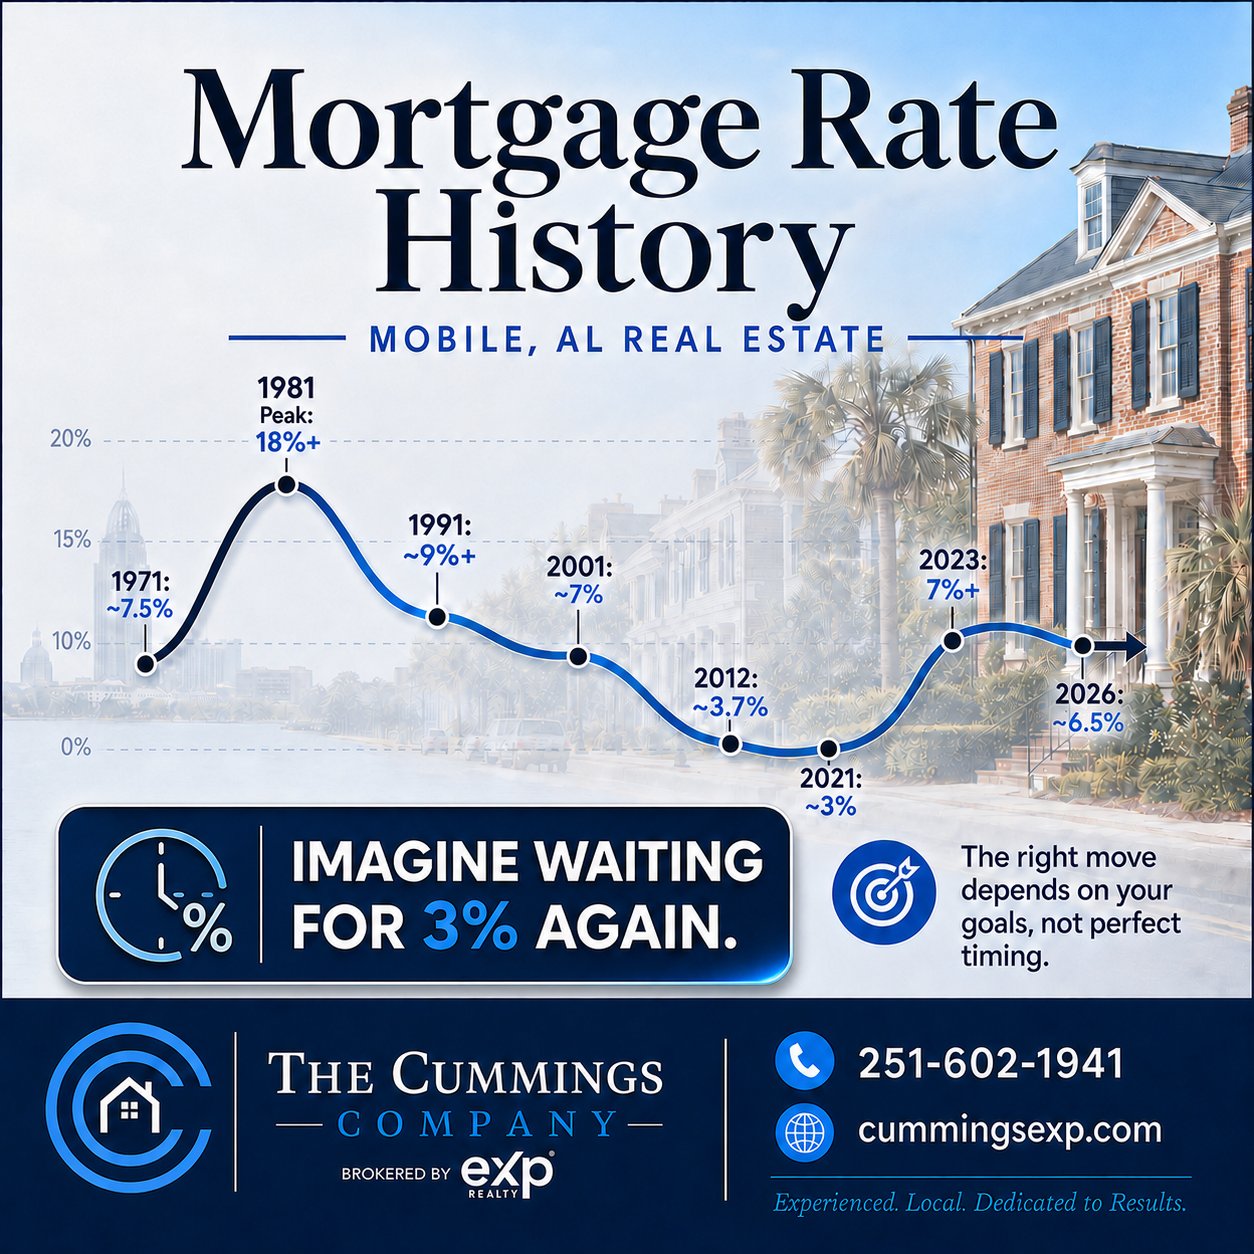
As of early June 2026, the average 30-year fixed mortgage rate is sitting between 6.37% and 6.56%, according to national surveys by Bankrate. That's down from the 7.80% peak in October 2023, but still elevated compared to the pandemic-era lows many buyers remember.
The big question everyone asks: When will rates drop?
Here's the honest answer — no one knows for certain. Morgan Stanley strategists forecast that rates could ease to around 5.50%–5.75% by mid-2026, but then rise again in the second half of the year. Norada Real Estate's 90-day forecast for May–July 2026 calls for rates to stay in the low-to-mid 6% range, with no dramatic drops expected in the near term.
Even if rates do fall, the savings may not be as significant as families expect — especially when you factor in what's happening to home prices in the meantime.
Mobile, AL Home Prices Are Already Rising
While buyers wait for rates to fall, Mobile's home prices are quietly climbing.
According to Redfin, the median sale price of a home in Mobile hit $220,000 in early 2026 — up 4.3% year-over-year. Price per square foot jumped even more sharply, rising 15.4% compared to the previous year.
And a Reddit thread from March 2026 noted what local residents are already feeling firsthand: Mobile is in a housing shortage, and prices are reflecting that pressure.
That 4.3% annual increase means a home priced at $220,000 today could be worth $229,460 by this time next year — and that's before any rate-driven demand surge pushes prices higher.
The Real Math: What Does Waiting Actually Cost?
Let's put real numbers to this for Mobile buyers.
Scenario: $220,000 home, 20% down payment, 30-year fixed mortgage
Even if rates drop by half a point — which is not guaranteed — the higher home price eats up most of those savings and then some. And this assumes rates actually fall to 6.0%. If they stay flat or rise, the numbers get worse.
That's money Mobile families simply cannot get back.
The Equity You're Missing Every Month You Rent
Every month spent renting while waiting is a month you're not building equity.
The average rent in Mobile, AL is currently $1,400/month according to Zillow, with some sources placing median rent as high as $1,500/month per Realtor.com. Every dollar of that monthly rent payment goes to your landlord — not toward an asset you own.
Compare that to a mortgage payment in the same range: each payment builds equity, potentially earns tax deductions on mortgage interest, and lets you benefit from price appreciation you'd otherwise be watching from the sidelines.
If Mobile home values appreciate just 4% over the next 12 months on a $220,000 purchase, that's $8,800 in equity growth — equity a renter never sees.
"But Won't Lower Rates Bring More Competition?"
This is one of the most important points buyers overlook.
Right now, Mobile's housing market is competitive but not frenzied. Homes are selling in around 55 days with a sale-to-list price ratio of 97.4%. Buyers still have some negotiating room.
The moment rates drop significantly, demand surges. More buyers enter the market, multiple-offer situations become more common, and sellers gain leverage. The home you can buy today at $220,000 with reasonable negotiating power could become a bidding war scenario at $230,000 or $235,000 — at only a slightly lower rate.
Lower rates don't just help you. They help every other buyer in the market too. And there are a lot of buyers waiting right now.
What Smart Mobile Buyers Are Doing Instead
The savvy move in 2026 isn't waiting — it's buying strategically and positioning for the future.
1. Buy now, refinance later.
If rates do drop to the 5% range in 2027 or beyond, you can refinance. You'll lock in today's price, build equity in the interim, and lower your payment when the time is right. This is the strategy many experienced buyers and real estate investors use consistently.
2. Negotiate seller concessions.
In today's market, sellers are sometimes willing to buy down your interest rate through seller-paid points or contribute to closing costs. Getting a rate buydown now can lower your payment immediately — without waiting on the Fed or bond markets to cooperate.
3. Explore FHA and VA loan options.
For buyers with lower down payments or VA eligibility, government-backed loans often offer rates slightly below conventional products. These programs make homeownership accessible now, not someday.
4. Focus on total cost, not just rate.
The rate is just one variable. The purchase price, your down payment, property taxes, and HOA fees all factor into your true monthly cost. A lower price today at a 6.5% rate may outperform a higher price next year at 5.9%.
Is the Mobile Market Right for You Right Now?
Mobile's housing market has a lot working in buyers' favor that often gets overlooked in national headlines:
Median home prices ($220,000) are 45% below the national average, per Redfin
Overall cost of living is 11% below the national average
The market is active but not extreme — homes sell in 55 days on average, giving buyers time to be deliberate
Mobile's inventory is growing, giving buyers more options than in past years
If you're a first-time buyer, a growing family, or someone who's been renting for years, Mobile may be one of the most accessible mid-size markets in the Southeast — and that window may narrow as more buyers recognize it.
Frequently Asked Questions
Should I wait for mortgage rates to drop before buying a home in Mobile, AL?
Waiting for rates to drop can feel logical, but it carries real financial risk. If home prices in Mobile continue rising at the current 4.3% annual rate, the higher purchase price can offset or exceed any savings from a lower rate. Most buyers who wait to time the market end up paying more overall.
What is the average home price in Mobile, AL in 2026?
As of early 2026, the median home sale price in Mobile, AL is approximately $220,000, up 4.3% year-over-year according to Redfin data.
What are mortgage rates expected to do in 2026?
Most forecasts for mid-2026 project 30-year fixed mortgage rates to remain in the low-to-mid 6% range, between 6.2% and 6.5%. Some forecasters see a possibility of rates dipping toward 5.50%–5.75% briefly, but also expect rates to rise again later in 2026 and into 2027.
Is it a good time to buy a house in Mobile, Alabama?
For buyers who are financially ready, Mobile's relatively affordable prices, growing inventory, and moderate competition make 2026 a reasonable time to buy. Waiting for a perfect rate environment may cost more than it saves.
What is the "buy now, refinance later" strategy?
This approach means purchasing a home at today's prices to lock in your equity and stop paying rent, then refinancing your mortgage when interest rates drop to a level that meaningfully lowers your payment. It separates the decision to buy from the decision to keep a specific rate permanently.
The Bottom Line for Mobile Families
Waiting feels safe. But in real estate, waiting has a price — and in Mobile's market right now, that price is often measured in thousands of dollars of lost equity, higher future purchase prices, and months of rent payments that build nothing for your family's future.
That doesn't mean every buyer should rush. It means every buyer should make a decision based on the full financial picture — not just the hope that rates will fall enough to make a meaningful difference.
If you're a Mobile-area family thinking about buying a home and wondering whether now is the right time for your situation, let's talk. I can help you run the real numbers for your budget, your neighborhood, and your goals.
Ready to stop waiting and start building equity?
Contact Ryan Cummings at The Cummings Company, brokered by eXp Realty — serving Mobile, Alabama and the surrounding Gulf Coast.
Data sources: Redfin Mobile Housing Market Report (Feb 2026), Bankrate National Mortgage Rate Survey (May 2026), Morgan Stanley Housing Forecast (Jan 2026), Norada Real Estate 90-Day Rate Forecast (May 2026), Zillow Mobile Rental Market Trends (May 2026), Realtor.com Mobile County Market Data.